All Categories
Featured


Holistic Retirement Strategies for 2026
Frequently review and change both your retirement cost savings and life insurance coverage to align with changing life situations and financial objectives. Comprehending the differences between retirement strategies and life insurance coverage is vital for efficient financial preparation. By Carl Lachman, CFP, MBAIt is possible to put a lot of cash into part of a particular type of life insurance coverage policy, let the money grow tax-free for years, then take the cash out tax-free when you retire.
It is not a method to determine who the excellent guys and bad guys are, however rather simply a method to identify who has met the minimum requirements for being able to sell insurance. Insurance agents are accredited to offer and get a commission for their sales. If they offer an insurance plan, they get.
paid. A much better way to get suggestions is to consider an authorized investment advisor. These experts (like me)generally provide detailed financial planning suggestions and handle your financial investments. They are lawfully required to follow the fiduciary requirement, putting your interests before their own interests. And, they are not paid by commissionexceeds the tax basis will be subject to tax);(3)withdrawals taken during the first 15 policy years do not cause, occur at the time of, or during the two throughout prior very first, any reduction in benefitsTrigger and Happen4)the policy does not throughout a modified endowment contract. Any policy withdrawals, loans, and loan interest will decrease policy worths and may decrease benefits. Life Insurance coverage: Death benefits are usually tax-free for beneficiaries; some policies use tax-deferred cash worth development.
Regularly review and change both your retirement cost savings and life insurance coverage to line up with changing life situations and monetary goals. Comprehending the distinctions in between retirement plans and life insurance coverage is important for effective financial planning. By Carl Lachman, CFP, MBAIt is possible to put a lot of money into part of a particular type of life insurance policy, let the cash grow tax-free for years, then take the cash out tax-free when you retire.
It is not a method to determine who the excellent guys and bad guys are, however rather just a method to determine who has fulfilled the minimum requirements for being able to sell insurance coverage. If they offer an insurance coverage policy, they getpaid. This money constructs up in the policy far above the yearly expense of the policy.
Frequently evaluation and adjust both your retirement savings and life insurance coverage to align with altering life situations and monetary objectives. Understanding the distinctions in between retirement plans and life insurance is essential for efficient monetary planning. By Carl Lachman, CFP, MBAIt is possible to put a lot of cash into part of a specific type of life insurance coverage policy, let the cash grow tax-free for years, then take the money out tax-free when you retire.
It is not a method to identify who the heros and bad guys are, however rather simply a way to identify who has actually met the minimum requirements for being able to sell insurance. Insurance coverage agents are licensed to sell and receive a commission for their sales. If they offer an insurance coverage, they get.
Long-Term Care Planningpaid. A better way to get recommendations is to consider an authorized investment consultant. These specialists (like me)typically offer comprehensive monetary preparation suggestions and manage your financial investments. They are lawfully needed to follow the fiduciary standard, putting your interests before their own interests. And, they are not paid by commission, but most are rather "fee-only,"which indicates they charge their clients an annual cost and do not earn money in any other method. In the case of this insurance/retirement technique, you pay thousands and countless dollars above the premium. This money develops in the policy far above the yearly cost of the policy.

Latest Posts
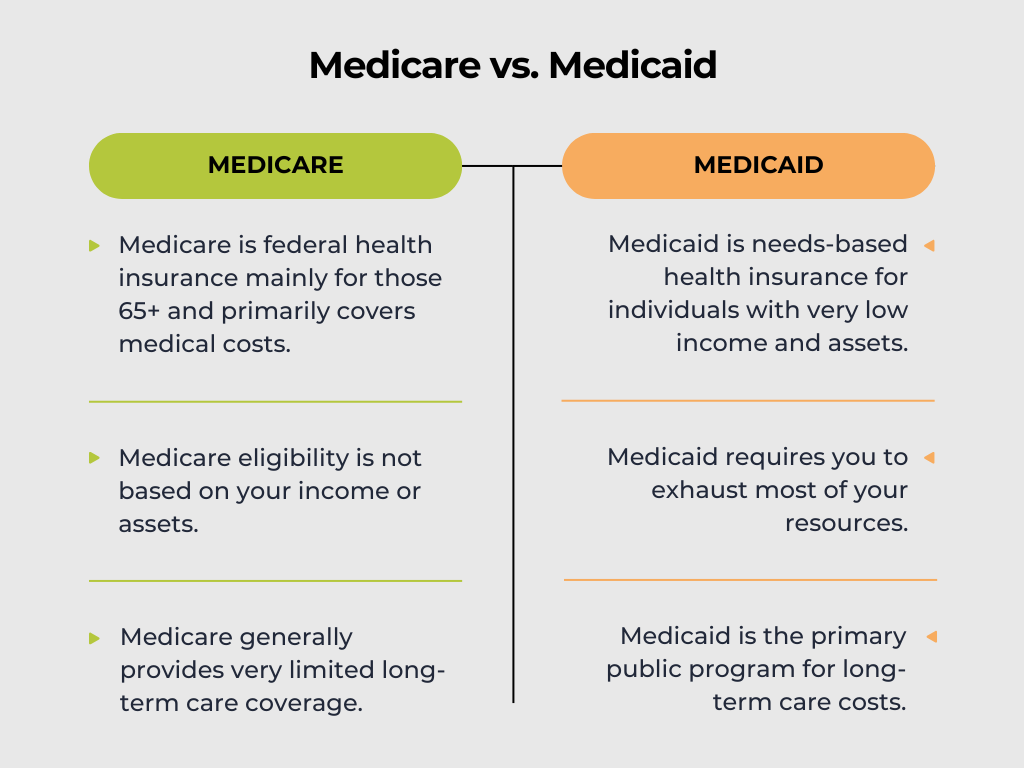
Why Your Medicare Supplement Needs a Hospital Add-on
How to Prepare for Upcoming Long-Term Care Expenses
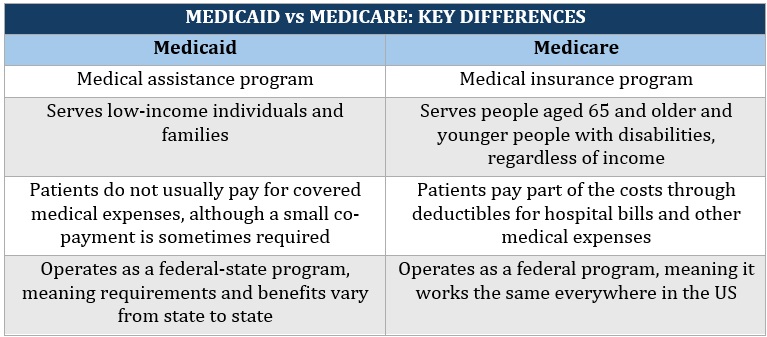
Managing Rising Medical Rates in 2026