All Categories
Featured
Table of Contents
Variable Annuities are sold by prospectus just. **The performance of variable sub-accounts is not guaranteed, and variable annuities are subject to market danger, consisting of loss of principal.
Annuities are among the most typical monetary items currently available in the market. Their complicated structure and the sometimes-questionable strategies utilized to market fixed and variable annuities can cloud financiers' understanding of these distinct products.
repaired annuities in detail outlining their structure, expenses, liquidity, tax implications, and suitability. Before diving deeper into the nuances of annuities, let's very first break down the difference between fixed vs. variable annuities. While there are lots of differences between set and variable annuities (as well as some resemblances) and there are a variety of various variations of each type, the primary characteristic that separates repaired and variable annuities is the method which the agreement value modifications in time (and hence, the worth of the cash flows that ultimately make money to the contract owner).
Owners of repaired annuities understand at the time of their purchase what the value of the future capital will be that are generated by the annuity. Obviously, the number of capital can not be understood beforehand (as this relies on the contract owner's life-span), however the ensured, fixed rates of interest at least gives the owner some level of certainty of future income from the annuity.
While this distinction appears easy and straightforward, it can substantially impact the value that an agreement owner ultimately originates from his/her annuity, and it creates considerable unpredictability for the agreement owner. It also usually has a product influence on the level of fees that a contract owner pays to the providing insurance provider.
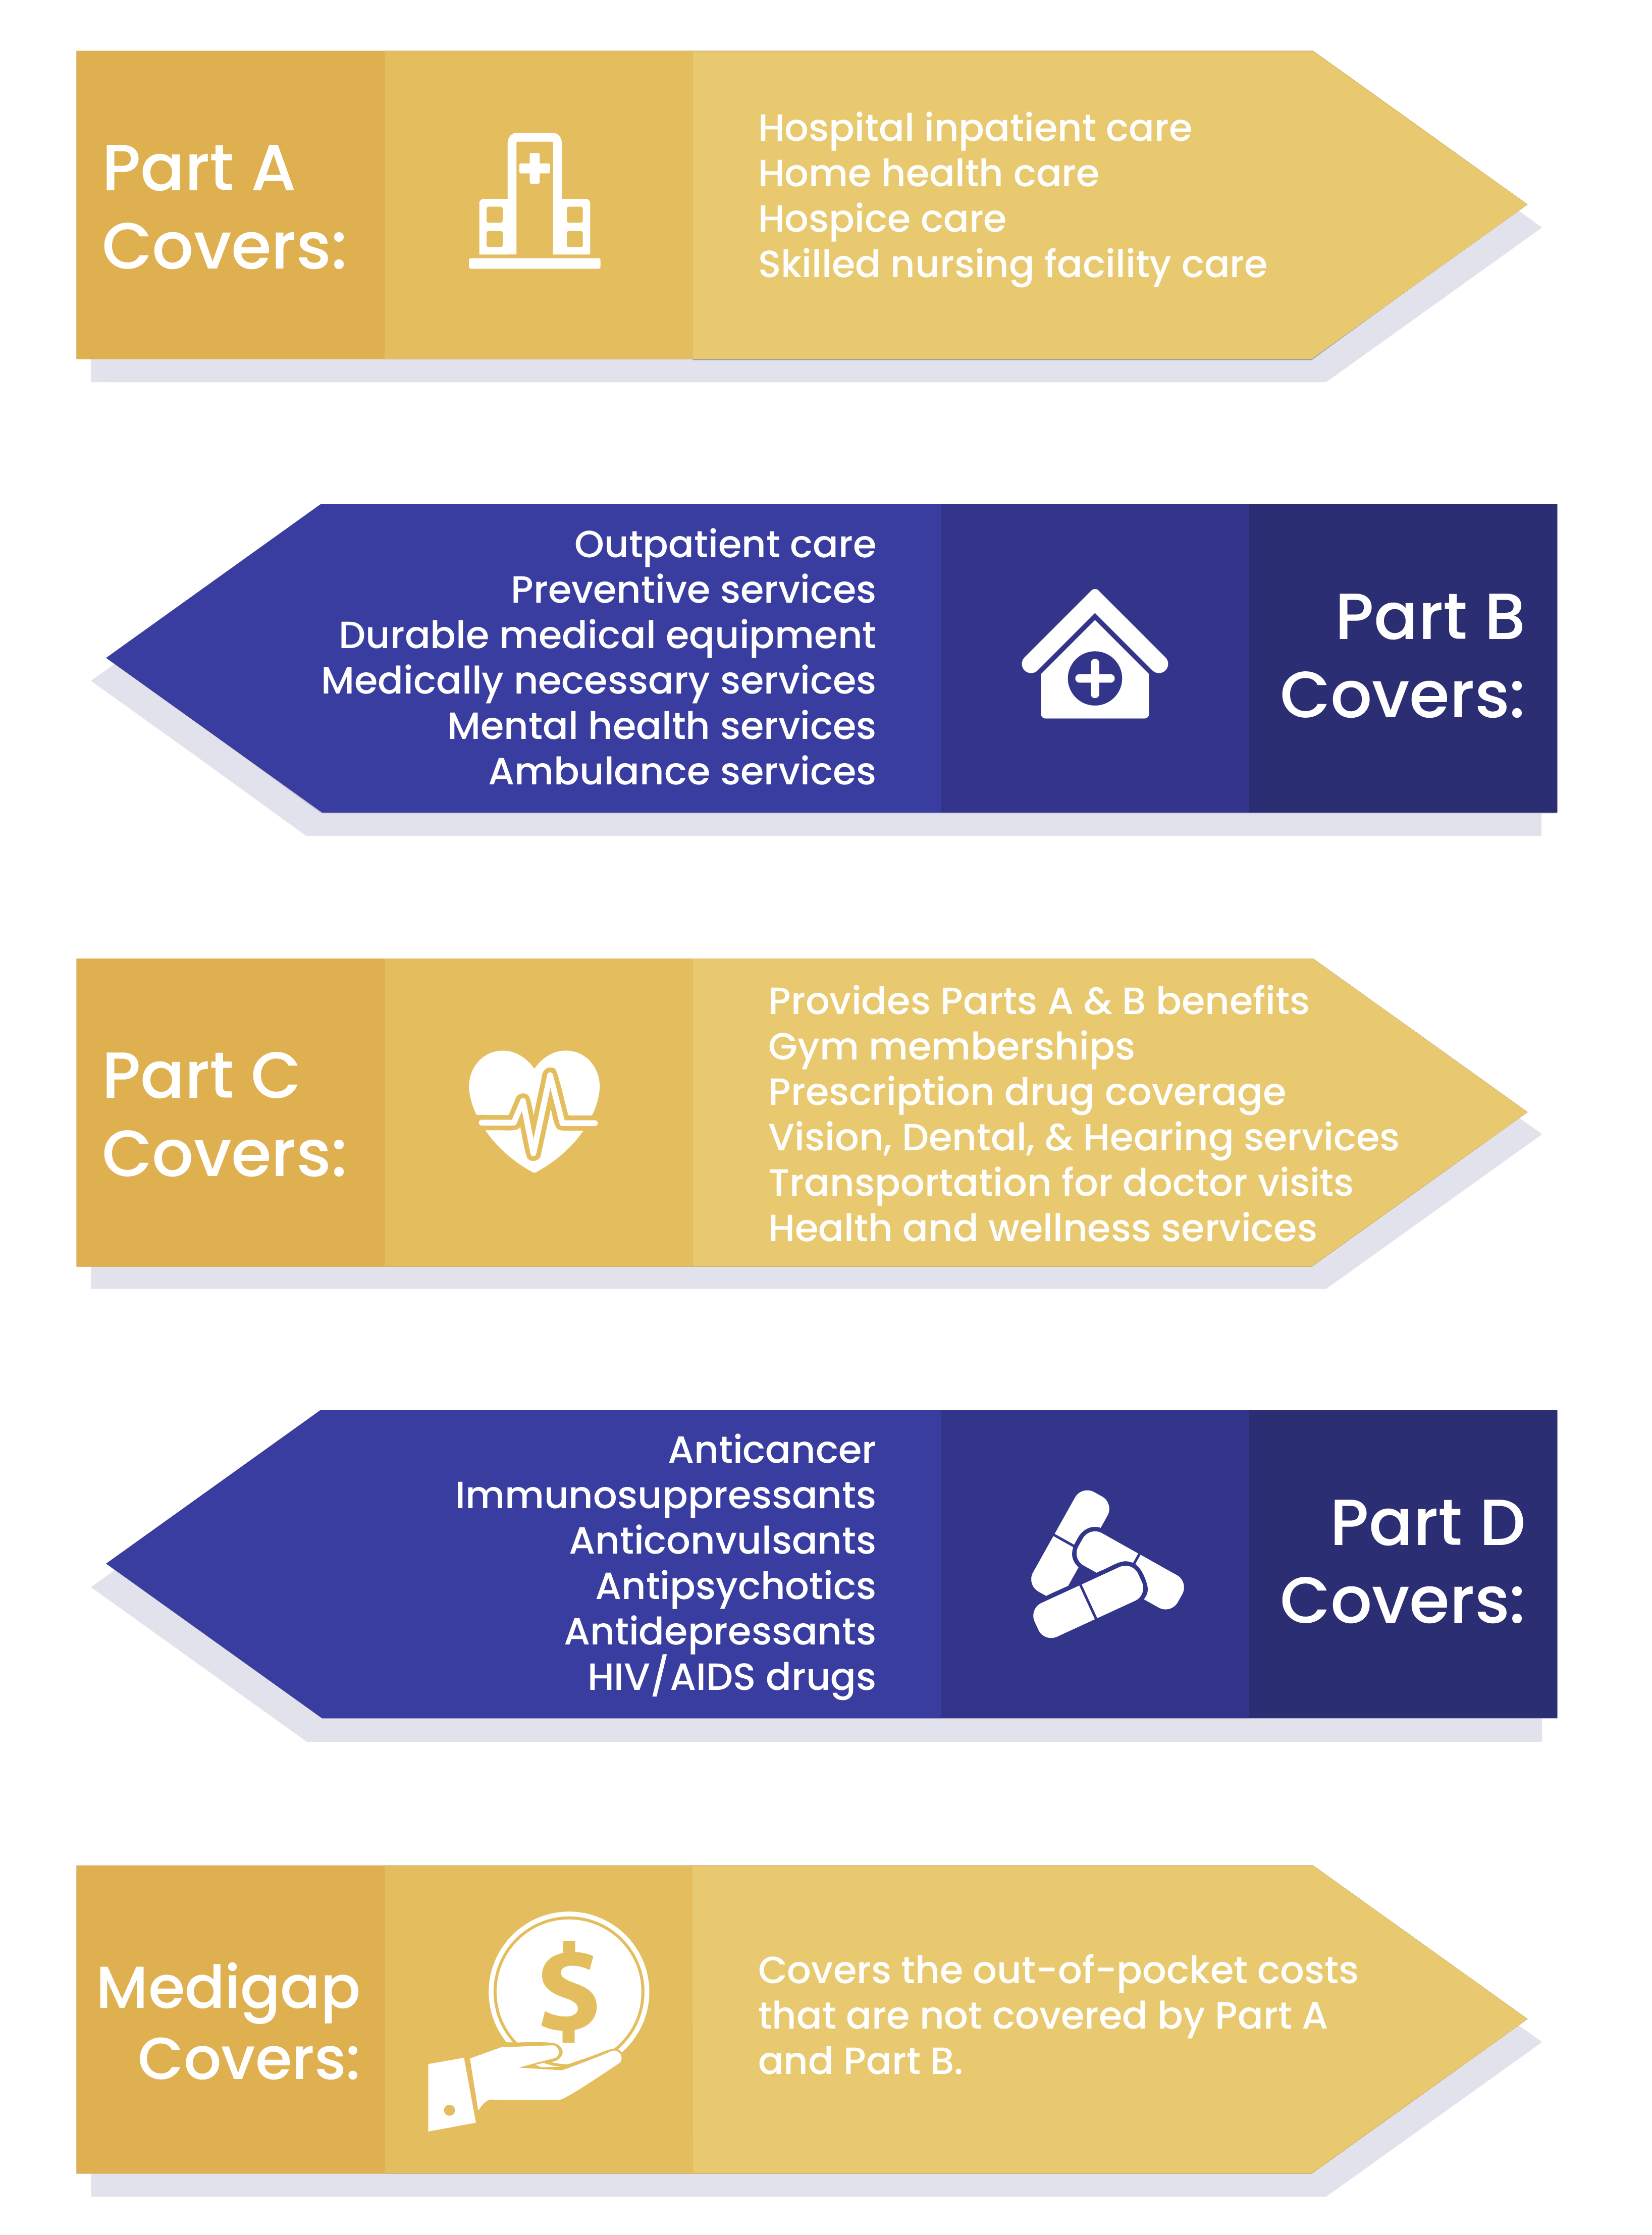
Long-Term Care Insurance Versus Medicare for Elderly Care
A fixed annuity is a contract in between a consumer and an insurer in which the insurance company concurs to pay the contract owner a set amount of income over a specific amount of time in exchange for either a one-time lump sum payment or series of payments in time.
There are 2 basic types of fixed annuities: immediate annuities and postponed annuities. The main distinction in between the two is the timing of the first payments made by the insurance coverage business to the contract holder. As the name suggests, the owner of an immediate annuity contract starts to receive annuity payments instantly upon acquiring the annuity contract.
A deferred annuity is an agreement that binds the issuing insurance business to pay the agreement owner a stream of money streams starting at a fixed date in the future. In between the time of purchase and the time when payments commence, a deferred fixed annuity boosts in worth based on the cumulative payments made into the annuity and an ensured, repaired rate of return.
Fixed annuities are often used by older financiers who have limited assets however who wish to offset the danger of outlasting their properties. Fixed annuities can serve as a reliable tool for this function, though not without specific downsides. In the case of immediate annuities, when a contract has actually been purchased, the contract owner gives up any and all control over the annuity possessions.
Retirement Planning Riverside CA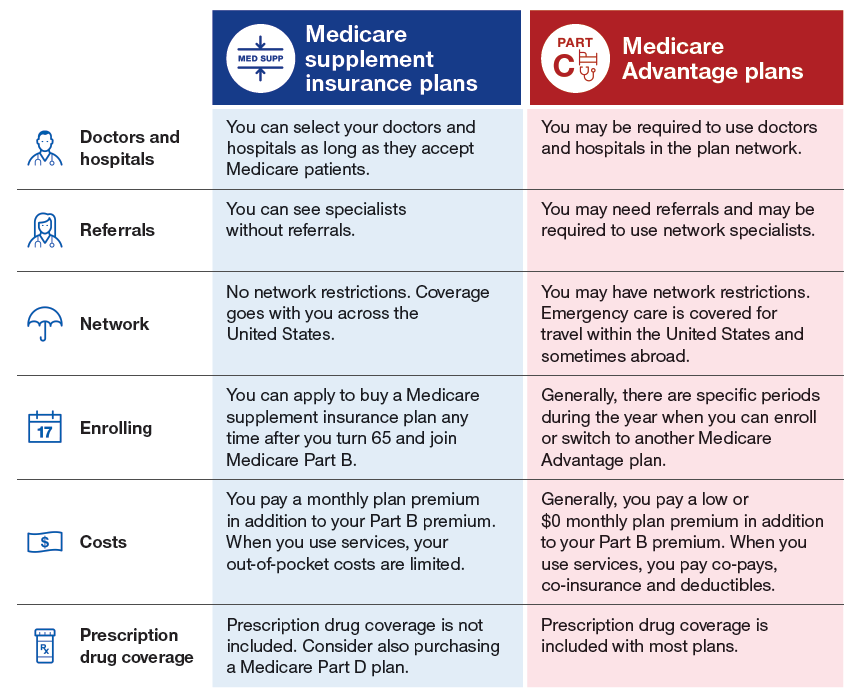
Specific annuity contracts might allow owners to borrow versus future cash flows, however these arrangements are generally really limited and might have adverse tax repercussions. Deferred annuities also come with their own liquidity concerns. Deferred annuities usually have a surrender period (10 years is most typical) that begins right away after the agreement is bought.
Maximizing Retirement Income With Annuities
An agreement with a typical 10-year surrender duration would charge a 10% surrender charge if the agreement was surrendered in the first year, a 9% surrender charge in the 2nd year, and so on until the surrender charge reaches 0% in the agreement's 11th year. Some delayed annuity contracts contain language that enables little withdrawals to be made at numerous periods during the surrender duration without penalty, though these allowances normally come at a cost in the type of lower surefire interest rates.

Latest Posts
Managing Out-of-Pocket Expenses in a High-Cost Era
Exploring Variable Annuity for 2026
How Fontana Seniors Hedge Against Economic Shifts